
Commercial Real Estate Loan Requirements and Eligibility
Securing capital for commercial property acquisition or refinancing requires satisfying structured eligibility benchmarks set by commercial lenders. Unlike consumer home loans—which rely predominantly on personal W-2 income and personal debt-to-income (DTI) metrics—commercial property underwriting evaluates both sponsor creditworthiness and the cash-generating capacity of the asset.
Understanding standard commercial real estate loan requirements helps investors and business owners prepare complete applications, negotiate favorable loan terms, and avoid costly approval delays.
This guide outlines core credit score minimums, Debt Service Coverage Ratio (DSCR) benchmarks, equity down payment rules, and essential financial documentation required by underwriters.
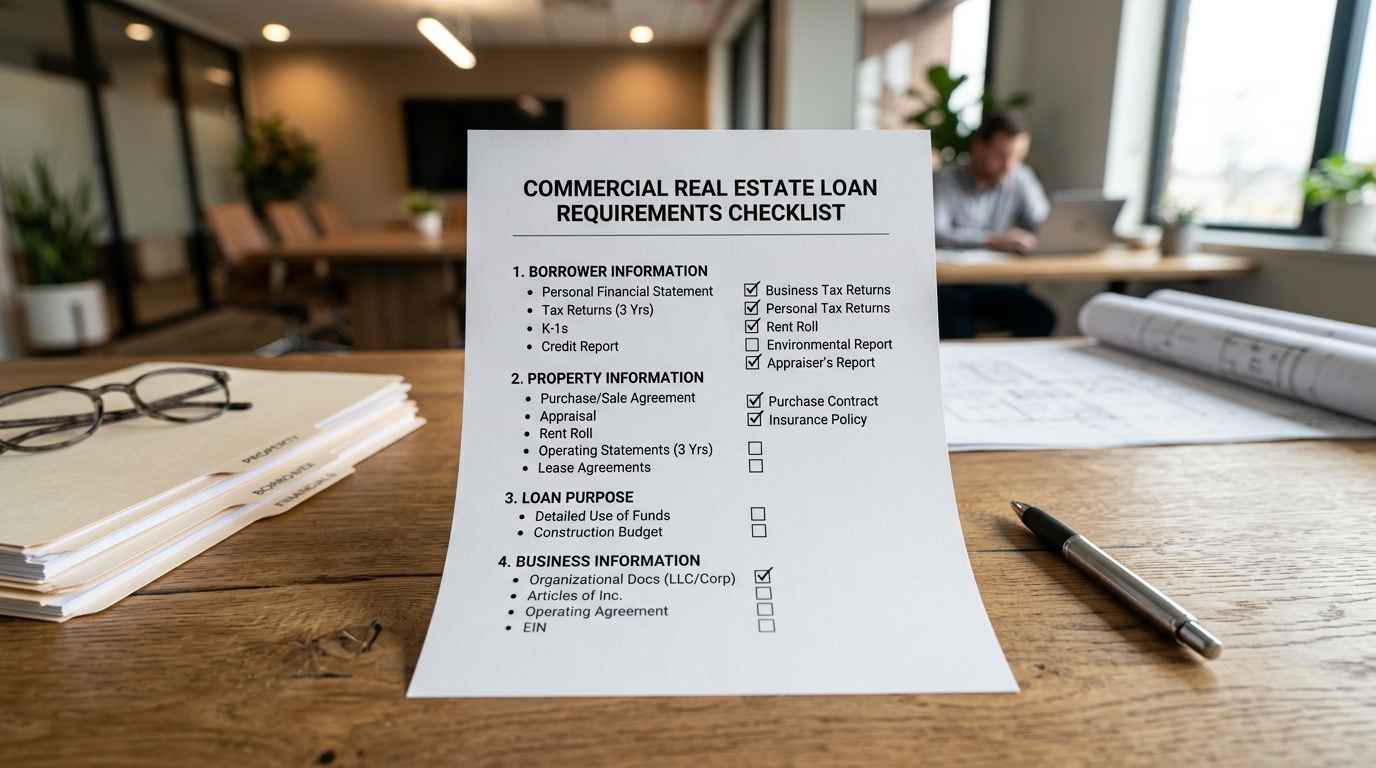
Key requirements and documents for commercial real estate loan applications.
Standard Commercial Real Estate Loan Eligibility
To qualify for commercial real estate financing, both the property and the borrowing entity (or individual guarantors) must satisfy primary underwriting standards. Lenders evaluate financial strength across four main categories:
- Property Income Potential: The real estate must demonstrate sufficient current or prospective Net Operating Income (NOI) to meet monthly debt obligations comfortably.
- Sponsor Equity & Liquidity: Borrowers must contribute meaningful equity (down payment) and maintain post-closing cash reserves.
- Creditworthiness & Track Record: Principal guarantors must possess strong personal credit histories and relevant real estate management experience.
- Property Quality & Location: Lenders inspect asset condition, environmental status, zoning compliance, and local market demand fundamentals.
Personal and Business Credit Score Minimums
While commercial mortgages are tied to property cash flow, guarantors holding 20% or more ownership in the borrowing entity undergo credit checks.
Credit Score Expectations by Lender Type
- Conventional Banks & Credit Unions: Prefer personal credit scores of 680 to 720+.
- SBA Loan Programs (7a & 504): Typically require minimum credit scores around 650 to 680.
- CMBS / Conduit Lenders: Often set minimum threshold credit benchmarks around 660, placing heavier emphasis on asset performance and DSCR.
- Commercial Bridge & Private Lenders: Offer flexibilities down to 600 to 620, focusing primarily on property equity and collateral value.
In addition to personal credit, lenders evaluate business credit profiles (Paydex scores, Experian Commercial credit) for established operating entities seeking business real estate loans.
The Importance of DSCR (Debt Service Coverage Ratio)
The Debt Service Coverage Ratio (DSCR) is arguably the single most vital metric in commercial loan underwriting. DSCR evaluates a property’s financial capacity to pay its mortgage payments relative to its net operating income:
$$\text{DSCR} = \frac{\text{Net Operating Income (NOI)}}{\text{Annual Debt Service}}$$
                       Net Operating Income (NOI)
     DSCR =  ───────────────────────────────────────────────
             Annual Principal + Interest + Tax + Insurance
Standard DSCR Benchmarks
- Minimum Target (1.20x – 1.25x): Conventional lenders usually mandate a minimum DSCR of 1.25x. This means net revenue must equal 125% of annual principal and interest debt service, providing a 25% buffer against potential tenant vacancies or rising expenses.
- High-Risk Asset Target (1.35x – 1.50x): Special-use properties (such as hotels, restaurants, or single-tenant assets) may require higher DSCR margins due to operating cash flow volatility.
- Below 1.00x DSCR: Indicates negative cash flow where property revenues cannot cover loan obligations without external capital injections.
To compare how different funding options calculate minimum coverage standards, review our overview of commercial real estate loan options.
Commercial Real Estate Loan Down Payment Expectations
Down payment requirements in commercial real estate are generally higher than consumer residential mortgages. Lenders manage financial exposure by requiring equity contributions from the borrower.
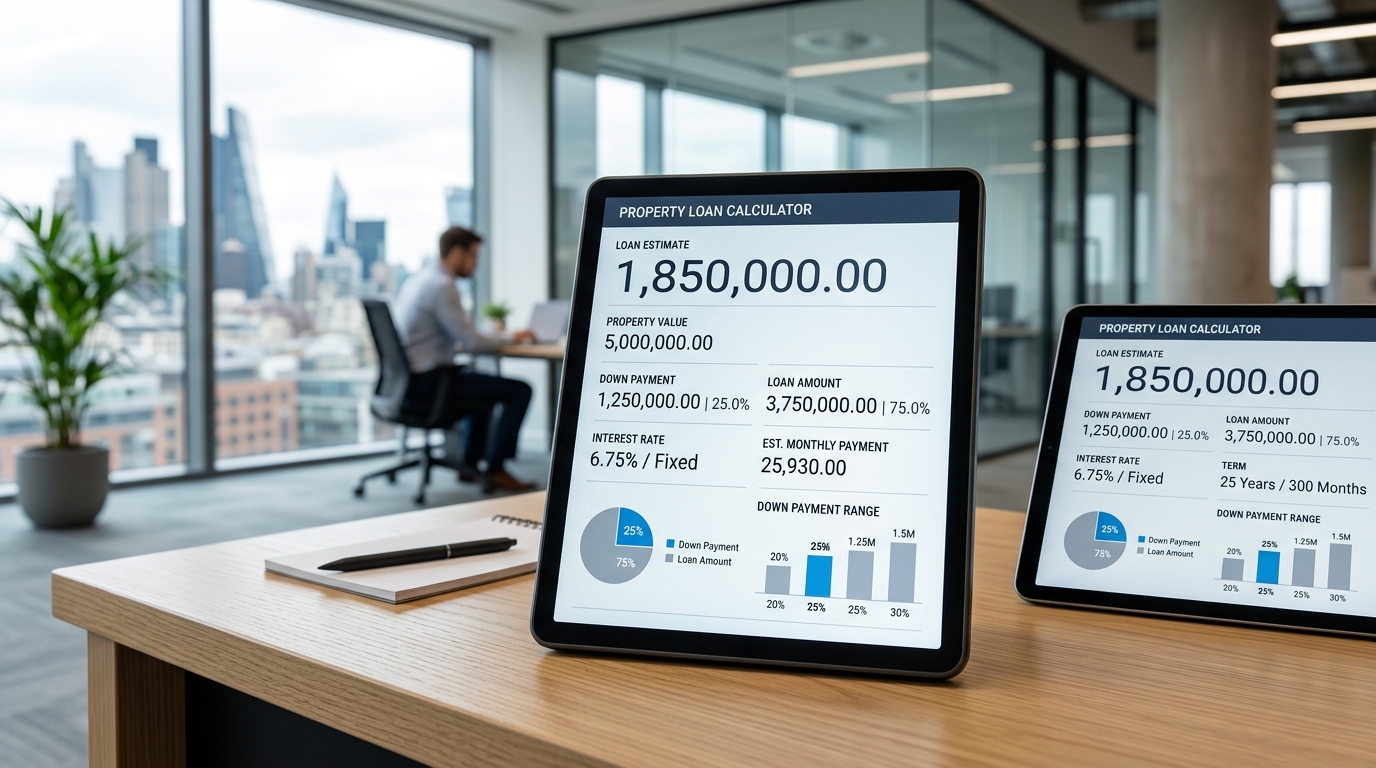
Visualizing down payment expectations for commercial real estate loans.
Typical Down Payment Percentages
- Conventional Commercial Mortgages: Require 20% to 35% down (65% to 80% Loan-to-Value).
- SBA 504 & 7(a) Owner-Occupied Loans: Require as little as 10% to 15% down (up to 90% Loan-to-Value).
- Commercial Bridge Loans: Require 20% to 30% down based on total purchase price or loan-to-cost (LTC).
Where Can Your Down Payment Come From?
Lenders strictly audit the source of equity capital. Acceptable equity sources include:
* Liquid business or personal cash savings held in verified bank accounts.
* Equity raised from limited partners or equity syndicate members.
* 1031 tax-deferred exchange proceeds from prior property sales.
* Refinanced equity drawn from existing real estate portfolios.
Borrowed funds (such as unsecured secondary loans) are generally prohibited from serving as equity down payments unless approved under specific mezzanine debt structures.
Required Documentation for Approval
A complete, organized submission packet accelerates underwriting timelines and demonstrates sponsor professionalism. Lenders typically request documentation across three categories:
1. Borrower & Sponsor Documentation
- 3 years of personal and business federal tax returns for all guarantors (>20% owners).
- Current Personal Financial Statements (PFS) outlining personal assets and liabilities.
- Color copy of government photo ID and entity organizational documents (Articles of Organization, Operating Agreement, FEIN letter).
2. Property Financial Documentation
- Current detailed rent roll specifying tenant names, square footage, lease expiration dates, and lease rates.
- 3 years of historical year-end property Profit & Loss (P&L) statements.
- Year-to-date interim income and expense statements.
- Copies of current commercial tenant lease agreements.
3. Real Estate Transaction Documents
- Fully executed Purchase and Sale Agreement (PSA) for property acquisitions.
- Property tax assessments and municipal water/sewer bills.
- Existing floor plans, site surveys, and preliminary architectural drawings (if renovating).
Understanding requirements is the first step in mastering the entire commercial real estate loan application process.
Frequently Asked Questions
What is the minimum down payment for a commercial real estate loan?
For owner-occupied properties financed through SBA loan programs, down payments start at 10%. For investor-owned commercial properties financed through conventional bank loans, down payments typically range from 20% to 35%.
What DSCR do banks look for on commercial real estate?
Most commercial banks look for a minimum DSCR of 1.25x on stabilized commercial properties. This ensures the property generates 25% more net operating income than required to make annual principal and interest payments.
Can I qualify for a commercial real estate loan with bad credit?
Yes. If your personal credit score is below 650, you can still secure commercial real estate financing through private lenders, hard money capital, or bridge lenders. These entities emphasize property equity, asset value, and post-closing cash reserves over personal credit scores.
What cash liquidity is required post-closing for a commercial loan?
Lenders usually require post-closing liquid cash reserves equal to 6 to 12 months of total debt service payments (principal, interest, taxes, and insurance) held in unencumbered deposit accounts.