
How to Calculate & Negotiate Commercial Loan Closing Costs
Accurately forecasting closing costs is one of the most vital steps in structuring a successful commercial real estate investment. Miscalculating upfront transaction costs can lead to cash flow shortfalls, forced equity injections, or worst of all, failed transactions at the closing table.
Furthermore, unlike residential purchases where closing fees are largely rigid, commercial real estate deals offer significant room for negotiation. Smart investors know how to calculate expected fees precisely and leverage market dynamics to reduce closing expenses.
In this actionable guide, we break down the 4-step commercial calculation formula, clarify buyer vs. seller fee allocations, and share proven strategies for negotiating lender and third-party costs.
Step-by-Step Calculation Formula for CRE Closing Costs
Calculating commercial mortgage closing costs requires combining percentage-based points with fixed third-party diligence fees and variable municipal taxes.

A clear, step-by-step formula is essential for accurately calculating commercial real estate closing costs, ensuring all financial aspects are covered.
How do you calculate commercial loan closing costs?
Featured Answer / Step-by-Step Formula:
To calculate total commercial real estate loan closing costs, follow these 4 steps:
1. Calculate Lender Fees: Multiply your loan amount by expected origination points (typically 0.5%–1.5%), then add fixed administrative processing and underwriting charges ($1,500–$3,500).
2. Add Third-Party Diligence Reports: Sum estimated costs for required reports (Commercial Appraisal: $2,500–$6,000+; Phase 1 ESA: $2,000–$4,500; ALTA Survey: $2,000–$5,000; Engineering Report: $2,500–$5,000).
3. Calculate Legal, Title, and Escrow Fees: Budget 0.5%–1.0% of the property purchase price for borrower legal counsel, lender legal counsel, title search fees, and lender’s title insurance.
4. Add Government Taxes and Escrow Reserves: Include municipal recording fees, state transfer taxes, and 3 to 6 months of required property tax and insurance escrow reserves.
Who Pays Closing Costs on Commercial Property?
Unlike residential real estate where local customs strictly dictate fee split rules, commercial fee allocations are governed by negotiation in the Purchase and Sale Agreement (PSA).
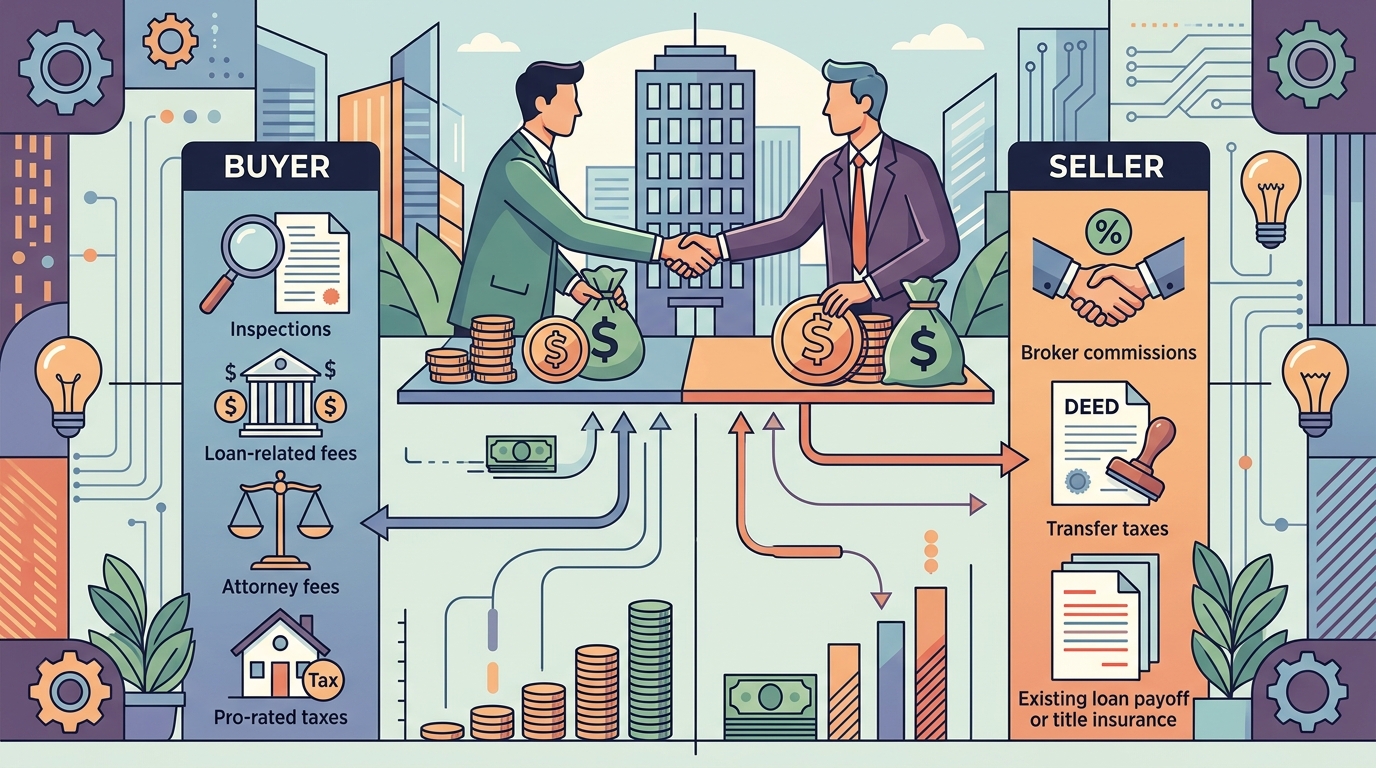
Understanding the typical allocation of closing costs between buyers and sellers in commercial property deals is crucial for effective negotiation.
Buyer vs. Seller Allocation
In standard commercial transactions, fee responsibilities generally split as follows:
- Buyer (Borrower) Responsibilities:
- Loan origination points, underwriting fees, and lender legal counsel.
- Commercial appraisal fee and Phase 1 Environmental Site Assessment (ESA).
- Property condition assessment (PCA) and structural inspections.
- ALTA land title survey and lender’s title insurance policy.
- Buyer’s attorney fees.
- Seller Responsibilities:
- Real estate broker commissions (typically paid entirely by seller).
- Owner’s title insurance policy (customary in many states, though negotiable).
- Outstanding property taxes and utility charges prorated up to the day of closing.
- Seller’s attorney legal fees.
- Negotiable / Split Expenses:
- Government transfer taxes and recording fees (often split 50/50 depending on local market practices).
- Escrow officer and settlement closing fees.
Strategies for Negotiating Lender Fees and Third-Party Costs
Because commercial lenders and vendors operate in a competitive free market, experienced real estate sponsors routinely negotiate fees to lower upfront capital requirements.
How can borrowers negotiate commercial loan closing costs?
FAQ / Actionable Negotiation Tactics:
Borrowers can reduce commercial closing costs using four proven strategies:
1. Request a Binding Fee Cap on Lender Legal Expenses: Before executing a term sheet, require the lender to insert a clause capping lender legal counsel fees (e.g., “Lender attorney fees billed to borrower capped at $5,000”).
2. Leverage Competing Lenders for Origination Points: Solicit 2 to 3 term sheets simultaneously. Requesting a 0.50% origination fee instead of 1.0% can save $10,000 on a $2 million loan. For deeper info on lender fees, see our detailed guide.
3. Re-Certify or Update Recent Diligence Reports: If an appraisal or Phase 1 ESA was completed within the last 6 to 12 months, ask your lender if the existing vendor can issue a recertification or update letter for a fraction of the full report cost.
4. Select Independent Title and Escrow Vendors: Do not automatically default to lender-recommended title companies. Shop independent commercial title agencies for competitive endorsement rates and settlement charges. For deeper info on reports, consult our diligence breakdown.
How to Cap Pre-Closing Out-of-Pocket Expenses
One of the largest risks for commercial investors is spending $15,000+ on appraisals, environmental reports, and legal retainers only for a deal to fall apart during underwriting.
To minimize risk, implement these cash-protection mechanisms:
* Incorporate Due Diligence Contingencies: Ensure your PSA gives you 30 to 45 days of due diligence during which your earnest money deposit remains 100% refundable.
* Stage Third-Party Report Orders: Order the Phase 1 ESA first ($2,500) before authorizing a $5,000 appraisal order. If an environmental REC surfaces, you can cancel the deal before incurring appraisal expenses.
* Request Refundable Application Deposits: Require that unused portions of lender underwriting deposits be returned if credit approval is denied.
Sample Closing Statement Calculation Example
Consider a sample calculation for a $2,500,000 Commercial Acquisition with a $1,875,000 Loan (75% LTV):
| Cost Item | Calculation Method | Estimated Amount |
|---|---|---|
| Lender Origination Fee | 1.0% of $1,875,000 Loan | $18,750 |
| Underwriting & Processing | Fixed Lender Fee | $2,500 |
| Lender Legal Counsel | Negotiated Cap | $5,000 |
| Commercial Appraisal | Third-Party Vendor Fee | $4,500 |
| Phase 1 Environmental ESA | Third-Party Vendor Fee | $3,000 |
| ALTA Survey | Third-Party Vendor Fee | $3,500 |
| Borrower Legal Counsel | Flat Fee / Billable | $5,000 |
| Title Insurance & Settlement | ~0.60% of Purchase Price | $15,000 |
| Transfer Tax & Recording | Municipal Allocation | $4,000 |
| TOTAL ESTIMATED CLOSING COSTS | ~3.2% of Loan Amount | $61,250 |
Calculate Your Custom Deal Costs
Ready to model your transaction’s exact closing costs? Use our free interactive commercial real estate closing cost calculator to generate a custom, itemized output instantly.