

The Complete Guide to Commercial Real Estate Loan Closing Costs
Acquiring or refinancing commercial real estate represents a major milestone for property investors, business owners, and syndicators. However, one of the most frequent friction points during a transaction is calculating the total capital required to reach the closing table. Beyond your primary down payment, commercial real estate loan closing costs can significantly impact your net liquidity and overall project return on investment (ROI).
Unlike residential mortgage transactions—where standardized disclosures like the Loan Estimate and Closing Disclosure mandate strict fee structures and strict caps—commercial loans involve bespoke underwriting, extensive property due diligence, and negotiation between sophisticated parties.
This comprehensive 2026 guide breaks down everything you need to know about cre loan closing costs, including percentage benchmarks, itemized expense categories, key differences from residential transactions, and practical strategies to budget for your transaction effectively.
What Are Commercial Real Estate Loan Closing Costs?
Commercial real estate loan closing costs encompass the full suite of administrative, legal, underwriting, and third-party due diligence fees required to finalize a commercial mortgage. These transaction costs are paid to various entities, including the lending institution, third-party diligence vendors (such as appraisers and environmental engineers), legal counsel, title companies, and local government municipalities.
When securing commercial financing—whether for retail centers, industrial warehouses, multi-family complexes, or office buildings—closing expenses fall into two primary cash flow timing categories:
- Pre-Closing Out-of-Pocket Expenses: Fees that must be paid upfront during the underwriting and due diligence phase, before loan approval or funding certainty (e.g., application deposits, appraisal deposits, and Phase 1 Environmental Site Assessments).
- Settlement Statement Closing Costs: Fees settled at the closing table on the final settlement statement, often netted from loan proceeds or paid as part of the buyer’s final equity bring-to-close.
Understanding these distinctions is essential for maintaining adequate working capital throughout the deal lifecycle.
Average Closing Costs on Commercial Property
A standard rule of thumb in commercial real estate is that closing costs generally range between 3% and 5% of the total loan amount (or roughly 2% to 4% of the total property purchase price).
However, because commercial transactions vary widely based on asset class, loan structure (SBA, agency, bridge, CMBS, or bank debt), and geographic location, closing costs can fluctuate above or below these general baselines.
| Loan Amount | Estimated Closing Cost Range (3% – 5%) | Expected Third-Party Diligence Share | Expected Lender & Legal Share |
|---|---|---|---|
| $1,000,000 | $30,000 – $50,000 | $8,000 – $15,000 | $15,000 – $25,000 |
| $2,000,000 | $60,000 – $100,000 | $10,000 – $20,000 | $35,000 – $60,000 |
| $5,000,000 | $150,000 – $250,000 | $15,000 – $35,000 | $90,000 – $175,000 |
| $10,000,000 | $300,000 – $500,000 | $25,000 – $50,000 | $200,000 – $380,000 |
What are average closing costs on commercial property?
Featured Answer / Benchmark Summary:
Average closing costs on commercial property typically range between 3% and 5% of the total loan amount. For a $2,000,000 commercial property loan, expected closing costs generally fall between $60,000 and $100,000. These costs comprise three main components: lender fees (0.5%–1.5%), third-party due diligence reports ($8,000–$25,000+), and title, legal, and government recording fees (1.0%–2.0%).
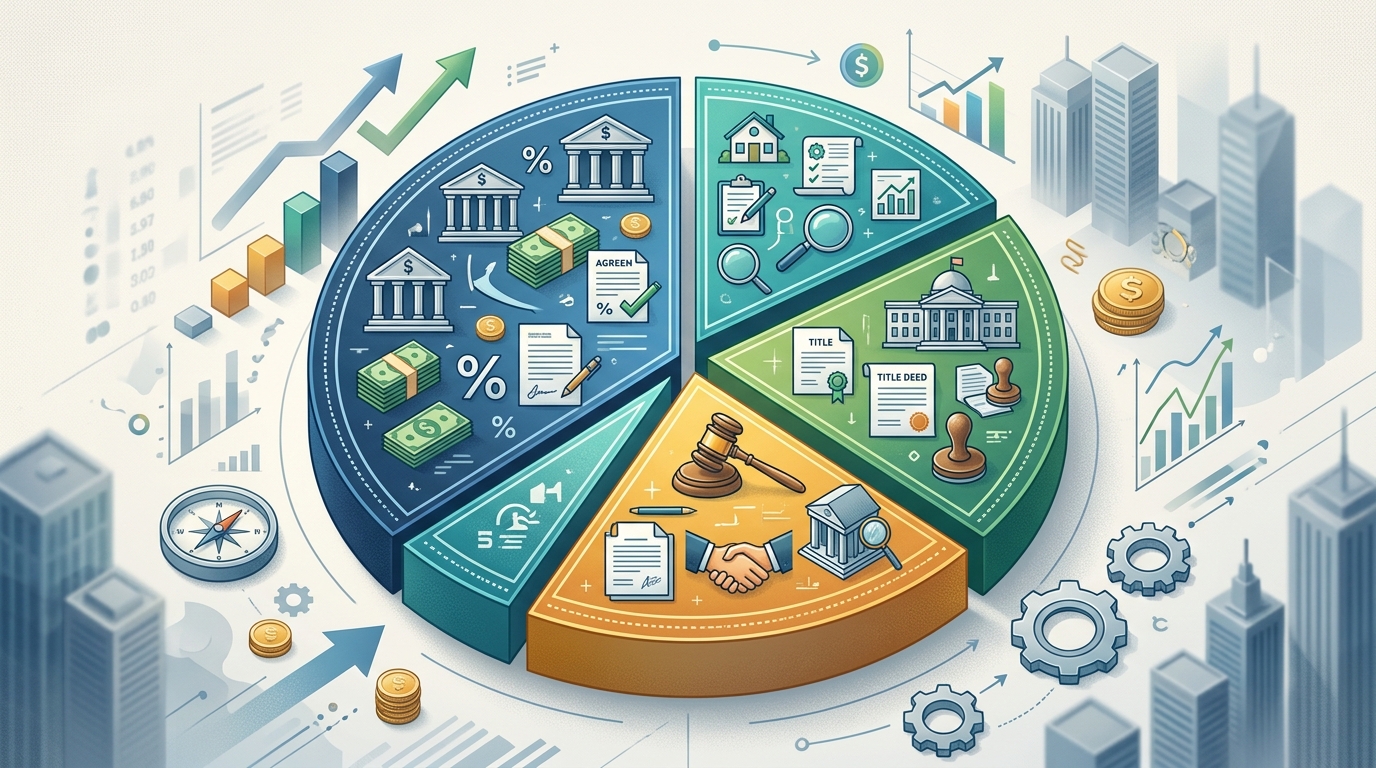
A visual breakdown of average commercial real estate loan closing costs, categorized into lender fees, third-party due diligence, and government/title fees.
Itemized Breakdown of Out-of-Pocket Transaction Costs
To accurately budget for commercial mortgage closing costs, it helps to categorize expenses into three core buckets: Lender Fees, Third-Party Due Diligence, and Government/Title Fees.
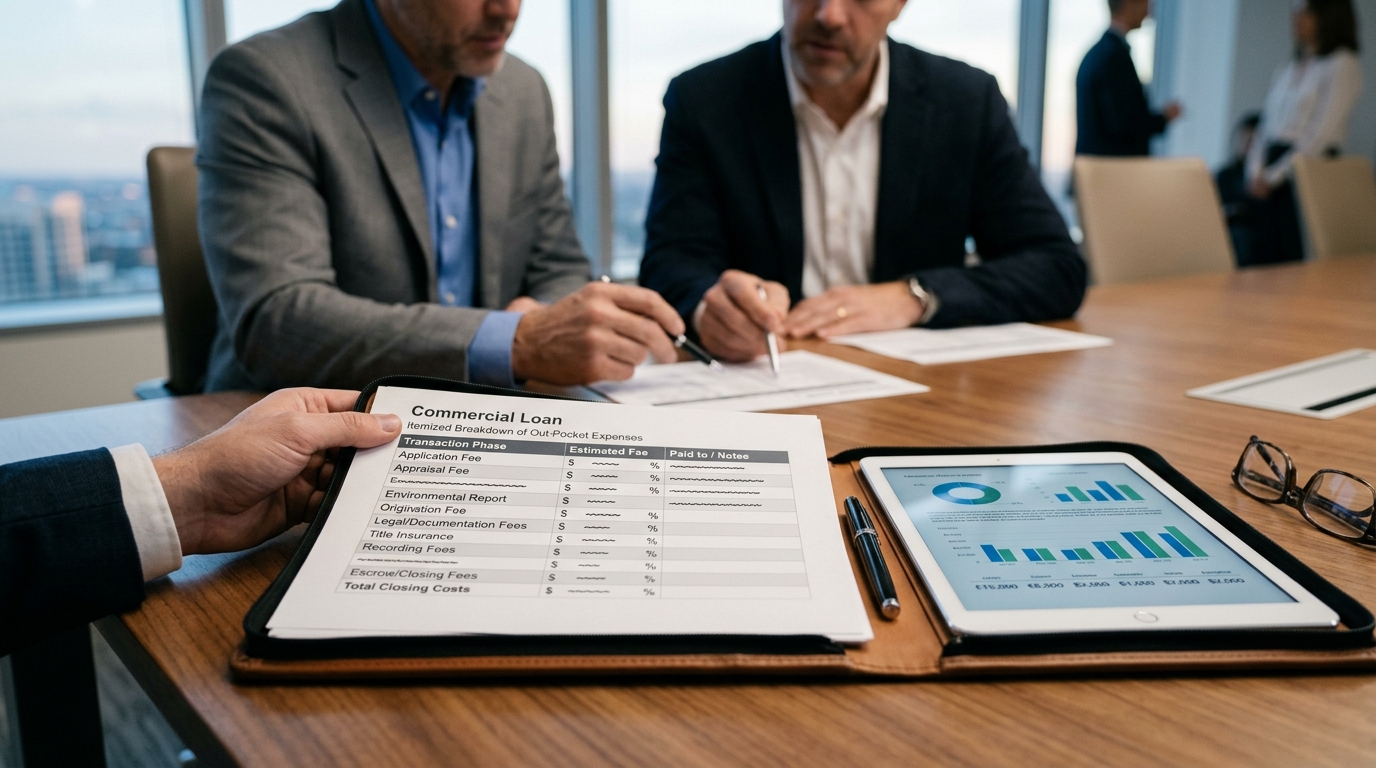
An itemized overview of the out-of-pocket expenses typically associated with securing a commercial real estate loan.
Lender Fees vs. Third-Party Expenses vs. Government Fees
1. Lender Fees (Direct Financial Institution Charges)
Lender-related expenses compensate the institution for evaluating risk, structuring the loan, and underwriting the transaction:
* Origination Fee: Typically 0.5% to 1.5% of the total loan amount. Cover loan processing, structuring, and administrative overhead. (For a deep dive into how these charges are assessed, see our guide on lender origination fees).
* Underwriting & Processing Fees: Administrative fees ranging from $1,500 to $3,500 for internal risk analysis and file processing.
* Lender Legal Counsel Fee: Lenders retain external law firms to draft loan documents, mortgage agreements, and guarantees. Borrowers pay this cost, which typically ranges from $3,000 to $10,000+.
* Rate Lock / Extension Fees: Charges associated with holding a specific interest rate prior to loan funding.
2. Third-Party Due Diligence Expenses
Third-party vendors perform independent reviews of the physical, environmental, and financial health of the commercial asset:
* Commercial Appraisal: $2,500 to $10,000+ depending on property size, complexity, and number of units.
* Phase 1 Environmental Site Assessment (ESA): $2,000 to $4,500 to evaluate environmental liability risks.
* ALTA/NSPS Land Title Survey: $2,000 to $6,000+ to establish exact boundary lines, easements, and encroachments.
* Property Condition Assessment (PCA) / Engineering Report: $2,500 to $6,000 for structural, HVAC, and roof evaluations.
* Credit & Background Checks: $250 to $750 per key principal or guarantor.
For complete pricing details across each diligence category, explore our dedicated breakdown of third-party expenses.
3. Government, Title, and Escrow Fees
These costs ensure clean title transfer, proper legal recording, and required reserves:
* Commercial Title Insurance Policy (Lender’s & Owner’s): 0.5% to 1.0% of purchase price or loan amount.
* Escrow & Settlement Fees: $1,000 to $3,000 paid to the closing attorney or escrow officer.
* Government Transfer Taxes & Recording Fees: Varies widely by jurisdiction (from nominal recording charges up to 2% of transaction value in high-tax municipalities).
* Initial Tax and Insurance Escrow Reserves: Lenders frequently require 3 to 6 months of property taxes and insurance premiums held in escrow at closing.
How CRE Closing Costs Differ from Residential Mortgage Costs
If you are transitioning from residential investing to commercial real estate, assuming closing fees will mirror residential norms is a costly mistake. Commercial real estate closing fees differ significantly in structure, governance, and expense level:
- Lack of Standardized Consumer Protections: Residential loans are governed by the Real Estate Settlement Procedures Act (RESPA) and TILA-RESPA Integrated Disclosure (TRID) rules, which strictly mandate fee caps and 3-day disclosure windows. Commercial loans are unregulated consumer transactions; terms and fees are determined by free-market negotiation and term sheet language.
- Lender Legal Costs Passed to Borrower: In residential transactions, lender legal expenses are built into administrative processing fees. In commercial real estate, the borrower pays the lender’s specialized legal counsel directly.
- Higher Third-Party Report Requirements: While a residential purchase requires a $500 home inspection and $600 appraisal, commercial transactions mandate specialized engineering, environmental, and commercial appraisal reports that often exceed $10,000 combined.
- Negotiability: Because commercial agreements are customized, many lender administrative fees and closing terms can be capped or negotiated prior to signing the term sheet.
Frequently Asked Questions
What are out-of-pocket expenses for a commercial loan?
Out-of-pocket expenses for a commercial loan refer to upfront capital that a borrower must pay out of pocket during the loan application and underwriting period before the loan is closed or funded.
Common pre-closing out-of-pocket expenses include:
* Application / Underwriting Deposit: $2,500 – $5,000 paid to the lender to initiate review.
* Appraisal Fee Deposit: $3,000 – $8,000 collected upfront to order the commercial appraisal.
* Phase 1 Environmental Site Assessment (ESA): $2,000 – $4,500 paid directly to the environmental consultant.
* Property Condition Assessment (PCA): $2,500 – $5,000 paid to engineering vendors.
* Borrower Legal Retainer: $2,500 – $5,000 retainer paid to your attorney.
Note: If the loan fails to close due to property defects or borrower cancellation, these third-party out-of-pocket expenses are typically non-refundable.
Estimate Your Closing Costs Instantly
Planning your cash-to-close requirements doesn’t have to rely on guesswork. Use our interactive closing cost calculator tool to generate a customized, itemized breakdown of expected lender fees, third-party due diligence costs, and government charges tailored to your specific commercial deal structure.