
How to Read a Commercial Real Estate Term Sheet: Key Clauses & Terms
Receiving a term sheet from a lender is a major milestone in securing financing for a commercial real estate property. However, a term sheet—sometimes referred to as a letter of intent (LOI) or commitment summary—is far more than a polite estimate. It establishes the financial and legal framework for your entire commercial mortgage.
Knowing how to read a commercial real estate term sheet enables commercial investors and business owners to identify hidden expenses, evaluate risk exposure, and negotiate better lending conditions before committing thousands of dollars in non-refundable diligence fees in 2026.
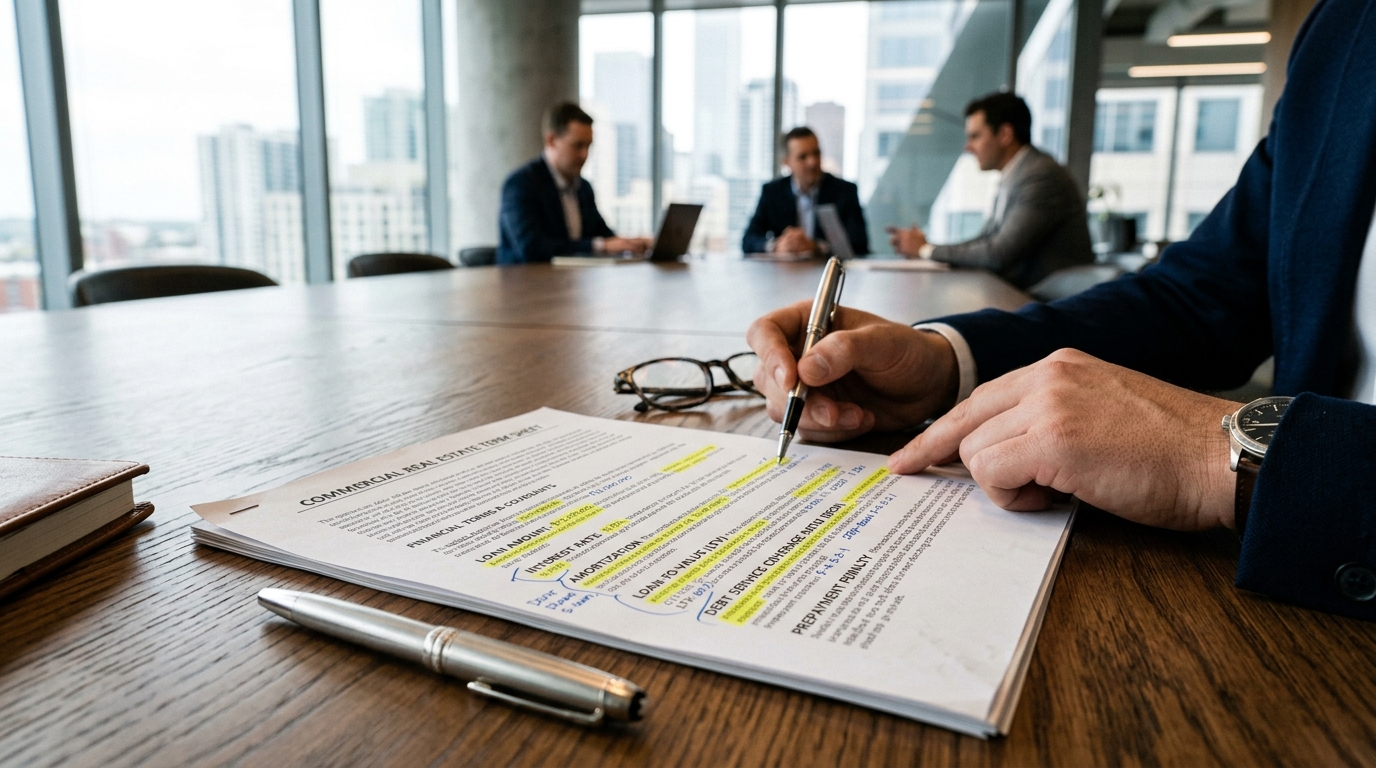
A commercial real estate term sheet outlines the core financial and legal framework for a commercial mortgage.
What is included in a commercial real estate term sheet?
A commercial real estate term sheet includes the borrower and lender identities, proposed loan amount, interest rate structure, loan duration, amortization schedule, recourse status, collateral description, required financial covenants, closing fees, and pre-closing underwriting contingencies.
It outlines all core parameters required to move a commercial loan application from preliminary discussion into formal underwriting and credit committee approval.
Binding vs Non-Binding Provisions
One of the most critical aspects of understanding commercial loan term sheets is distinguishing between binding and non-binding sections:
- Non-Binding Provisions: The vast majority of economic terms in a term sheet—including interest rate quotes, maximum loan-to-value (LTV) limits, loan duration, and amortization—are non-binding. The lender retains the right to adjust these terms based on appraisal results, property inspection findings, or environmental reports uncovered during formal underwriting.
- Binding Provisions: Specific administrative clauses are legally binding upon execution. These typically include exclusivity agreements (preventing the borrower from seeking other loan quotes for a specified period), confidentiality clauses, and liability for lender expense reimbursements (requiring the borrower to pay third-party legal, appraisal, and engineering fees regardless of whether the loan ultimately closes).
Reviewing standard commercial real estate loan terms before signing ensures you fully understand these baseline definitions.
Key Financial Conditions: Interest Rates & Duration
The financial conditions block forms the core economic engine of the term sheet. Below are the key clauses you must evaluate:
- Loan Amount & LTV Cap: The loan amount is typically expressed as the lesser of a fixed dollar amount, a maximum Loan-to-Value ratio (e.g., 75% LTV), or a minimum Debt Service Coverage Ratio (e.g., 1.25x DSCR).
- Interest Rate Structure & Index: Look closely at whether the interest rate is fixed or floating. Floating rates specify a spread above an index (e.g., 30-day SOFR + 250 basis points). Ensure you identify whether an interest rate floor exists (e.g., “Interest rate shall not drop below 5.50%”).
- Commercial Real Estate Loan Length (Term) & Amortization: The term specifies how long the lender provides financing (e.g., 5 or 10 years), while the amortization schedule determines monthly debt service payments (e.g., 25 years).
- Prepayment Penalty Structure: Term sheets explicitly state how early loan payoff is treated. Be alert for strict yield maintenance, defeasance, or step-down penalty clauses. For a full analysis of prepayment structures, read our guide on commercial real estate prepayment penalties.
What is recourse vs non-recourse in commercial real estate loan conditions?
In commercial real estate loan conditions, recourse determines whether a lender can pursue a borrower’s personal assets beyond the commercial property if default occurs. Recourse loans hold borrowers personally liable, while non-recourse loans limit lender recovery exclusively to the mortgaged property and its cash flow.
Effective negotiation of commercial real estate loan terms can lead to more favorable conditions for borrowers.
Comparative Analysis: Recourse vs. Non-Recourse
| Feature | Recourse Loan Conditions | Non-Recourse Loan Conditions |
|---|---|---|
| Borrower Personal Liability | Full personal financial liability for loan balance | Limited exclusively to property collateral |
| Lender Seizure Scope | Property + Personal bank accounts, real estate, liquid assets | Property collateral & property income streams only |
| Bad Boy Carve-Outs | N/A (Personal guarantee already covers full balance) | Active (Converts loan to recourse if fraud/bad acts occur) |
| Typical Loan Amounts | Under $2,000,000 – $5,000,000 | Over $5,000,000+ (CMBS, Fannie/Freddie, Life Co.) |
| Underwriting Focus | High emphasis on personal tax returns & net worth | High emphasis on property cash flow (DSCR) & asset quality |
What hidden fees or fine-print conditions exist in CRE term sheets?
Hidden fees and fine-print conditions in CRE term sheets include loan application fees, processing and commitment fees, lender legal reimbursement caps, third-party report charges, impound/escrow requirements, and post-closing financial covenants.
When examining the fine print, pay close attention to these easily overlooked cost items:
- Uncapped Lender Legal Fees: Term sheets often require borrowers to pay the lender’s outside legal counsel costs. Always negotiate a reasonable legal fee cap (e.g., “Lender legal fees capped at $10,000”).
- Third-Party Expense Commitments: Appraisals ($3,000–$7,000), Phase I Environmental Site Assessments ($2,500–$4,500), and Property Condition Assessments ($2,000–$5,000) are non-refundable expenses paid by the borrower prior to closing.
- Rate Lock Deposit Fees: Lenders may require a deposit (typically 1% of loan amount) to lock in interest rates prior to closing. Clarify under what exact conditions this deposit is refunded or credited toward closing fees.
- Ongoing Financial Covenants: Look out for ongoing covenants such as maintaining a minimum borrower net worth or liquidity standard, as well as annual property DSCR testing that could trigger a technical default if tenant vacancies increase.
How can borrowers negotiate commercial real estate loan terms?
Borrowers can negotiate commercial real estate loan terms by securing multiple lender quotes, requesting lower interest rate margins, reducing processing fees, capping lender legal expenses, and modifying restrictive financial covenants or prepayment penalty schedules before signing the agreement.
Strategic Steps for Successful Term Sheet Negotiation
- Leverage Multiple Lender Proposals: Never accept the first term sheet without competition. Obtaining competitive term sheets from bank, credit union, and private lenders creates immediate leverage to lower margins or eliminate application fees.
- Negotiate Fee Caps: Request firm dollar caps on internal processing fees, underwriting fees, and third-party legal expenses.
- Softener Recourse Guarantees: If full personal recourse is requested, negotiate to convert it into a burn-off guarantee (where recourse drops once property DSCR reaches 1.30x) or limit personal guarantees to a specific percentage of the outstanding loan.
- Flexibility on Prepayment Rules: Negotiate step-down prepayment penalties (e.g., 3-2-1%) in place of rigid yield maintenance formulas if you anticipate selling or refinancing within 3 to 5 years.
To navigate complex negotiation dynamics and customize your loan structure, speak with a commercial loan advisor.
Checklist: Questions to Ask Your Lender
Before signing a commercial real estate term sheet, ask your loan officer or broker these essential questions:
- [ ] Is this term sheet binding or non-binding regarding the interest rate and LTV?
- [ ] What specific third-party reports (Appraisal, Phase I ESA, PCA, ALTA Survey) are required, and what is the estimated total cost?
- [ ] Is there a dollar cap on lender legal fee reimbursements?
- [ ] What exact DSCR or financial covenants are tested post-closing, and how frequently are they evaluated?
- [ ] Under what circumstances is the application deposit or rate-lock deposit refundable?
- [ ] What is the exact prepayment penalty structure and calculation formula?
- [ ] Are there post-closing replacement reserve requirements or capital expenditure escrow impounds?
FAQ
Frequently Asked Questions
How long does a borrower have to sign a commercial loan term sheet?
Most commercial real estate term sheets contain an expiration date ranging from 7 to 14 days after issuance. If not signed with the required deposit submitted before expiration, the proposed interest rate and loan terms subject to change.
What is a good faith deposit in a CRE term sheet?
A good faith deposit (or processing deposit) is an upfront payment (typically $5,000 to $25,000 depending on deal size) submitted alongside the signed term sheet. It covers third-party appraisal, environmental, and underwriting costs incurred by the lender during formal due diligence.
Can a lender change the loan terms after a term sheet is signed?
Yes. Because key financial conditions in a term sheet are non-binding, a lender can adjust loan terms during final underwriting if appraisal values come in lower than expected, property inspection issues arise, or borrower credit verification yields discrepancies.
FAQ Schema (JSON-LD)
{
  "@context": "https://schema.org",
  "@type": "FAQPage",
  "mainEntity": [
    {
      "@type": "Question",
      "name": "What is included in a commercial real estate term sheet?",
      "acceptedAnswer": {
        "@type": "Answer",
        "text": "A commercial real estate term sheet includes borrower and lender details, loan amount, interest rate structure, loan duration, amortization schedule, recourse provisions, collateral descriptions, financial covenants, and fee schedules."
      }
    },
    {
      "@type": "Question",
      "name": "What is recourse vs non-recourse in commercial real estate loan conditions?",
      "acceptedAnswer": {
        "@type": "Answer",
        "text": "Recourse loans allow lenders to pursue personal assets beyond the property collateral if a default occurs, whereas non-recourse loans limit lender recovery strictly to the property and its income stream."
      }
    },
    {
      "@type": "Question",
      "name": "What hidden fees or fine-print conditions exist in CRE term sheets?",
      "acceptedAnswer": {
        "@type": "Answer",
        "text": "Hidden fees include loan application and processing fees, uncapped lender legal reimbursement, third-party appraisal and environmental report charges, and ongoing post-closing debt service covenants."
      }
    },
    {
      "@type": "Question",
      "name": "How can borrowers negotiate commercial real estate loan terms?",
      "acceptedAnswer": {
        "@type": "Answer",
        "text": "Borrowers can negotiate terms by obtaining multiple lender proposals, requesting fee caps on legal costs, softening personal recourse requirements, and modifying prepayment penalty structures."
      }
    }
  ]
}