
What Are Current Commercial Refinance Rates Today?
Commercial real estate owners face critical decision points when existing loans approach balloon maturity, interest rate reset dates, or when accumulated equity presents recapitalization opportunities. Analyzing commercial refinance rates today allows property sponsors to lower annual debt service, pull equity out for business expansion, or replace restrictive debt terms with long-term fixed capital.
This guide details current commercial real estate refinance rates, refinancing loan structures, closing cost calculations, and approval workflows.
What are current commercial refinance rates today?
In 2026, commercial refinancing rates range from [CURRENT_RATE]% to [CURRENT_RATE]% for conventional stabilized commercial assets. Exact pricing depends on property sector, Debt Service Coverage Ratio (DSCR), Loan-to-Value (LTV), and whether the transaction is structured as a simple rate-and-term refinance or a cash-out refinance.

An owner carefully reviews current commercial refinance rates to make informed financial decisions for their property.
Lenders pricing commercial refinance transactions evaluate market benchmarks alongside capital structures:
– Permanent Bank Refinancing: Fixed rates from [CURRENT_RATE]% to [CURRENT_RATE]% with 5-to-10-year terms.
– Agency Multifamily Refinancing: Rates from [CURRENT_RATE]% to [CURRENT_RATE]% with non-recourse execution up to 75% LTV.
– CMBS Refinancing: Fixed-rate pricing tied to 10-Year Treasury yields plus [CURRENT_RATE]% spreads for Tier-1 real estate.
Comparing these refinancing rates against benchmark average commercial real estate loan rates ensures your cash flow goals align with overall market trends.
Types of Commercial Mortgage Refinancing Options
Choosing the right structure among available commercial mortgage refinancing options depends on your financial goals, capital requirements, and property lifecycle stage.
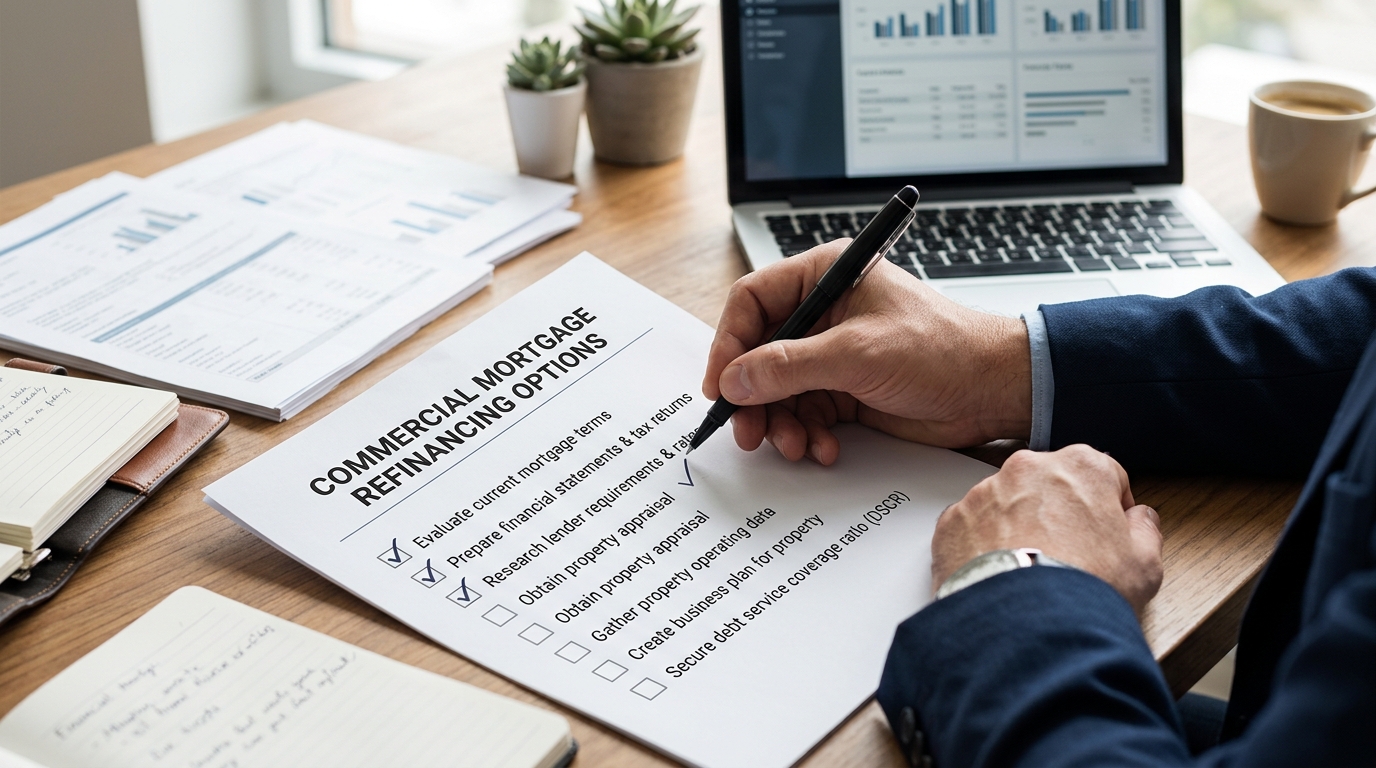
A detailed checklist outlining various commercial mortgage refinancing options, helping property owners navigate their choices.
Cash-Out Refinance Rates
A commercial cash-out refinance replaces existing debt with a larger loan, allowing the owner to convert equity into cash tax-free.
– Pricing: Commercial property cash-out refinance rates carry a slight rate premium (typically 25 to 50 basis points higher than rate-and-term options) due to higher risk from increased leverage.
– Maximum LTV: Typically capped at 65% to 70% LTV for commercial assets (up to 75% for multifamily).
– Primary Use Cases: Funding capital improvements (CapEx), funding property acquisitions, or returning equity to equity partners.
Rate and Term Refinance
A rate-and-term refinance modifies the interest rate, amortization schedule, or maturity term without increasing the principal loan balance.
– Pricing: Delivers the most competitive commercial refinancing rates available in the market.
– Maximum LTV: Available up to 75% or 80% LTV depending on asset class.
– Primary Use Cases: Lowering monthly debt payments, locking in fixed rates before variable loans adjust, or extending loan maturity schedules.
Property owners with apartment assets should evaluate dedicated multifamily commercial mortgage rates to access agency non-recourse pricing structures.
What fees and closing costs increase the effective APR?
When evaluating refinancing viability, property owners must calculate closing costs to ensure interest savings exceed transactional expenses.
Key costs impacting effective APR include:
- Lender Origination Fees: 0.50% to 1.00% of the net loan amount.
- Prepayment Penalties on Existing Loan: Step-down penalties (e.g., 3-2-1%), yield maintenance, or defeasance costs from your existing lender.
- Third-Party Due Diligence Reports:
– Commercial Appraisal: $3,500 – $8,000
– Phase I Environmental Site Assessment: $2,000 – $4,500
– Property Condition Assessment (PCA): $2,500 – $5,000 - Legal & Closing Costs: Lender counsel fees ($5,000 – $12,000) plus title insurance and recording taxes.
A successful refinance strategy amortizes these upfront closing costs over the new loan term while securing debt service savings.
When is the Right Time to Refinance a Commercial Loan?
Refinancing makes strategic sense when market conditions align with property performance metrics:
- 12 to 18 Months Before Loan Maturity: Refinancing early eliminates maturity default risk and avoids high floating rate extension fees.
- Substantial Property Value Appreciation: Unlocked equity can be reinvested without selling the underlying property asset.
- Significant Net Operating Income (NOI) Growth: Higher cash flow improves DSCR, unlocking prime loan rate brackets.
- Interest Rate Drops: Securing lower long-term fixed rates protects cash flows. Property owners holding floating-rate debt can transition away from variable commercial real estate rates to lock in operational predictability.
Refinance Application and Approval Process
Executing a commercial real estate refinance requires a structured 45-to-90-day underwriting workflow:
Step 1: Financial Preparation (P&L Statements, Rent Roll, Operating Statements)
       │
Step 2: Lender Term Sheet Negotiation & Soft Quote Selection
       │
Step 3: Third-Party Due Diligence (Appraisal, Phase I Environmental, Title Search)
       │
Step 4: Formal Underwriting & Credit Committee Approval
       │
Step 5: Document Closing & Existing Loan Payoff Execution
Preparing comprehensive rent rolls and historic financial statements early streamlines underwriting and secures competitive term sheet terms.
Frequently Asked Questions (FAQ)
What LTV is required for a commercial cash-out refinance?
Most commercial lenders cap cash-out refinancing at 65% to 70% LTV, though premier multifamily assets may qualify for up to 75% LTV.
How long does it take to refinance a commercial mortgage?
A standard commercial real estate refinance takes 45 to 75 days from signed term sheet to closing, largely determined by appraisal and due diligence turnarounds.
Are commercial refinancing fees tax-deductible?
Loan origination fees and closing costs associated with securing business debt are generally amortized over the life of the loan for tax purposes. Consult a CPA for guidance.
Can I refinance a commercial loan with a prepayment penalty?
Yes, but the prepayment penalty (yield maintenance, defeasance, or step-down) must be paid at closing out of refinance proceeds or borrower cash equity.