
Understanding Commercial Bridge Loan Terms & Structures
Navigating commercial real estate debt requires a clear understanding of loan structuring, index pricing, leverage thresholds, and covenants. Commercial bridge loan terms are specifically engineered to provide flexible capital during property acquisition, stabilization, repositioning, or debt payoff windows. However, because bridge loans carry higher risk profiles than long-term permanent debt, understanding structural parameters—such as Loan-to-Value (LTV) matrices, SOFR index spreads, extension options, and underwriting criteria—is vital for commercial real estate (CRE) sponsors.
This guide provides an in-depth breakdown of standard commercial bridge loan duration limits, leverage ratios, pricing indices, and borrower qualification requirements.
What are standard commercial bridge loan terms and duration limits?
Standard commercial bridge loan initial durations range from 12 to 36 months, with 24 months serving as the industry standard for light value-add transactions. Unlike long-term permanent mortgages amortized over 25 or 30 years, bridge loans are structured as short-term, interest-only (I/O) facilities.
Extension Options & Structure
To protect against project delays, most bridge lenders incorporate one, two, or three 12-month extension options into the loan agreement. Extension options allow sponsors to extend the maturity date subject to specific conditions:
- Extension Fee: Payment of an extension fee, typically 0.25% to 0.50% of the outstanding principal balance per 12-month extension.
- Debt Yield / DSCR Targets: Meeting minimum operational covenants, such as achieving a 9.0% minimum debt yield or a 1.25x Debt Service Coverage Ratio (DSCR).
- Interest Reserve Replenishment: Refilling the interest reserve account to cover ongoing interest payments during the extension period.
A visual timeline detailing the standard initial durations and potential extension periods for commercial bridge loans.
Commercial Bridge Loan LTV & Rate Matrices
Lenders utilize risk-adjusted matrix pricing, where higher leverage tiers correspond directly to higher interest rate spreads.
How does Loan-to-Value (LTV) impact commercial bridge loan rates?
Loan-to-Value (LTV) measures the ratio of total loan debt relative to the current appraised property value. For value-add deals, lenders also evaluate Loan-to-Cost (LTC) and As-Stabilized LTV (Loan-to-After-Repair-Value).
As LTV increases, lender capital exposure expands, resulting in higher interest rate premiums. The direct impact on average commercial bridge loan rates across different leverage tiers is illustrated below:
| Target LTV / LTC Tier | Relative Risk Tier | Typical Interest Rate Premium | Average Interest Rate Range | Common Minimum DSCR Target |
|---|---|---|---|---|
| Under 60% LTV | Low Risk | Baseline Pricing | 8.25% – 9.50% | 1.10x – 1.15x |
| 60% – 70% LTV | Moderate Risk | +50 to +100 bps | 9.00% – 10.50% | 1.15x – 1.20x |
| 70% – 75% LTV | Elevated Risk | +100 to +175 bps | 10.00% – 11.75% | 1.20x – 1.25x |
| 75% – 80%+ LTC | High Risk | +200 to +350 bps | 11.50% – 13.50%+ | Interest Reserve Required |
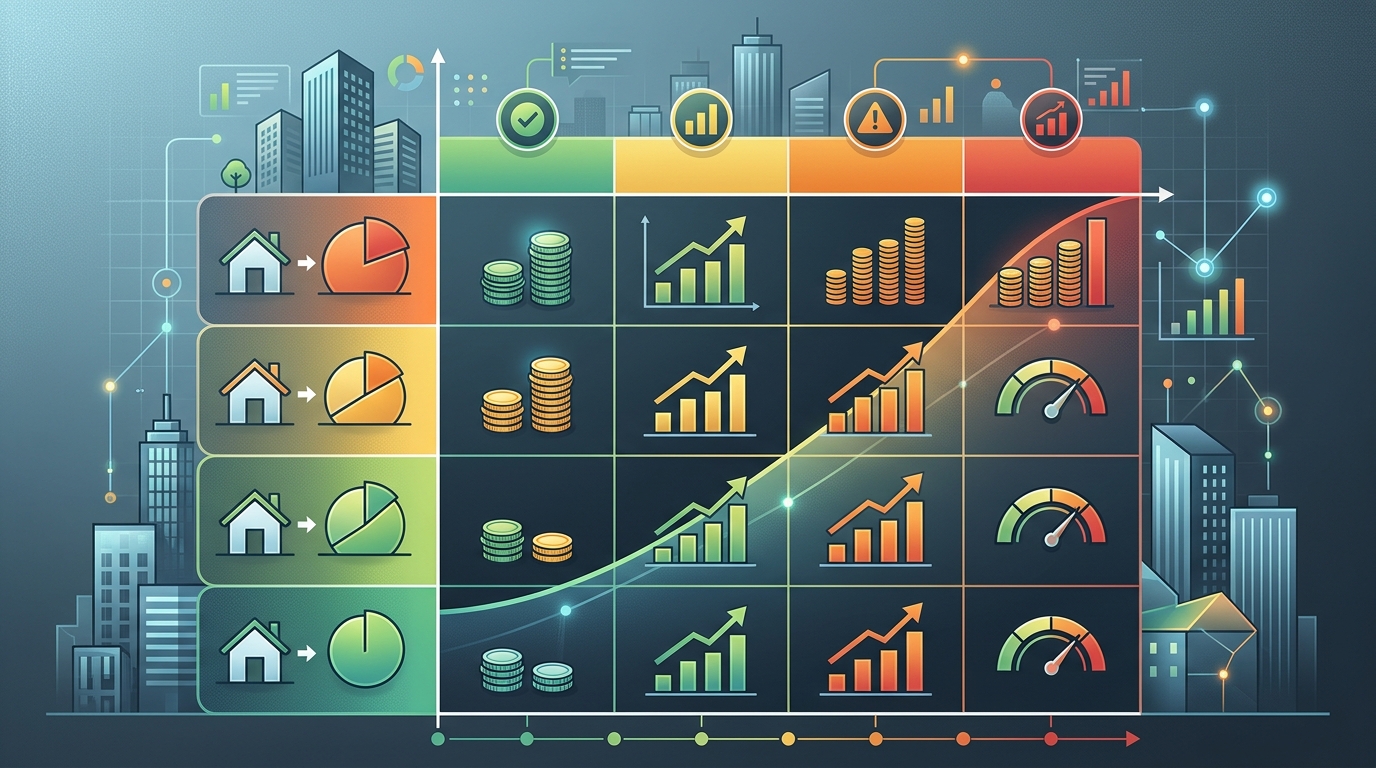
Understanding the impact of Loan-to-Value (LTV) on commercial bridge loan rates through a risk-adjusted matrix.
SOFR Index Spreads for Commercial Bridge Loans
The vast majority of commercial bridge financing issued by debt funds and institutional lenders is variable-rate debt benchmarked against the Secured Overnight Financing Rate (SOFR), specifically 30-Day Term SOFR. (Secured Overnight Financing Rate (SOFR))
What SOFR index spread is standard for commercial bridge loans?
Standard SOFR index spreads for commercial bridge financing typically range between 350 bps (3.50%) and 650 bps (6.50%) above 30-Day Term SOFR.
$$\text{Total Floating Interest Rate} = \text{30-Day Term SOFR Benchmark} + \text{Lender Spread}$$
Key Index Components:
- SOFR Benchmark Floor: If 30-day SOFR drops below the specified floor (e.g., 4.00%), the interest rate calculations freeze at the floor level plus spread.
- Interest Rate Cap Requirements: Lenders require borrowers to acquire an interest rate cap protection agreement from a recognized financial institution. This caps maximum SOFR exposure during the loan term, ensuring debt service protection if market benchmark rates surge.
Bridge-to-Permanent Loan Rate Structures
A bridge-to-permanent loan (or bridge-to-perm structure) combines short-term repositioning debt with an integrated option to convert into long-term permanent financing upon stabilization.
How does a bridge-to-permanent loan structure work and what are the rates?
In a bridge-to-perm deal, the loan transitions through two distinct phases:
- Bridge Phase (Months 1–24 or 36): The loan functions as a floating-rate, interest-only facility (rates between 8.50% and 11.50%). The sponsor uses this capital to complete property improvements and increase leasing occupancy.
- Permanent Phase (Years 3–10): Once the asset achieves stabilized occupancy (typically 90%+ for 90 days) and meets minimum DSCR targets (e.g., 1.25x), the loan automatically converts or refinances into standard fixed-rate debt (e.g., Fannie Mae, Freddie Mac, or bank permanent debt at rates between 5.75% and 7.25%).
This structural approach eliminates re-underwriting risk and reduces secondary closing costs, providing sponsors with a seamless execution roadmap.
Underwriting Requirements for Commercial Bridge Rates
Unlike traditional bank debt that relies primarily on historical cash flow, bridge loan underwriting heavily evaluates future asset potential, property location, and sponsor capability.
What minimum credit score and DSCR are required for a commercial bridge loan?
- Sponsor Credit Score: Lenders typically require key principals/guarantors to maintain a credit score of 680 or higher (720+ for optimal rate pricing).
- Net Worth & Liquidity Covenants: Sponsors must generally demonstrate a net worth equal to or exceeding 100% of the total loan amount, along with post-closing liquid assets equal to 5% to 10% of total debt.
- Debt Service Coverage Ratio (DSCR): During the initial bridge phase, starting DSCR can be below 1.0x (or even negative for total repositioning deals), provided an adequate Interest Reserve Account is established at closing. As-stabilized target DSCR expectations generally range from 1.20x to 1.30x.
Before finalizing credit application packages, borrowers should review a full breakdown of typical origination fees to ensure all capital needs and upfront costs are covered.
To test customized deal scenarios, sponsors can model terms in our bridge loan payment calculator.
Frequently Asked Questions (FAQ)
What is an interest-only bridge loan?
An interest-only bridge loan requires monthly payments covering only accrued interest costs rather than principal reduction. This structure maximizes cash availability during property renovations and stabilization phases.
What happens if I cannot exit my bridge loan before maturity?
If property stabilization takes longer than planned, sponsors can exercise contractually defined extension options (if performance targets are met), refinance into another short-term bridge facility, or negotiate a workout extension with the lender.
Are commercial bridge loans non-recourse?
Most institutional debt fund bridge loans over $3 million are non-recourse, meaning the lender’s recovery in default is limited to the property collateral. However, standard “bad-boy carve-outs” apply, holding guarantors personally liable in cases of fraud, environmental issues, or intentional bankruptcy filing.
What is an interest reserve account?
An interest reserve account is cash set aside at closing—funded by the loan proceeds or borrower equity—used to fund monthly debt service payments when initial property cash flow is insufficient to cover interest.