
A Complete Guide to Interest-Only Commercial Real Estate Loans
For commercial real estate investors seeking to maximize initial cash flow, execute value-add property renovations, or optimize investment yields, debt structure plays a pivotal role. Among specialized commercial debt structures, an interest only commercial real estate loan (or a loan with an initial interest-only period) stands out as a powerful financial mechanism.
Unlike standard fully amortizing commercial mortgages—where every monthly payment includes both principal reduction and interest—an interest-only (I/O) loan structure allows borrowers to pay exclusively interest charges for a predetermined timeframe.
This guide details how interest-only commercial loans operate, their key strategic benefits, potential risk exposures, lender qualification requirements, and how I/O phases transition into standard amortizing schedules.
How Does an Interest-Only Commercial Real Estate Loan Work?
Featured Snippet Definition:
An interest only commercial real estate loan is a mortgage structure where the borrower pays only the accrued interest charges each month, leaving the underlying principal loan balance unchanged. During the interest-only period (typically 1 to 5 years), monthly debt service is significantly lower than on a standard amortizing schedule. Once the I/O window expires, the loan either transitions into a fully amortizing schedule over its remaining term or matures requiring full principal payoff.
During the interest-only phase, borrowers pay only interest, leading to lower initial monthly payments.
Mechanics of the Interest-Only Phase vs. Amortizing Phase
To understand the mechanics, consider a $3,000,000 commercial mortgage written at a 6.00% fixed interest rate with a 10-year loan term based on a 25-year amortization schedule, featuring a 3-year interest-only period.
1. The Interest-Only Phase (Years 1 to 3)
During the first 36 months, no principal paydown occurs.
* Monthly Interest Calculation:
$$\text{Monthly Payment} = P \times \left(\frac{r}{12}\right) = \$3,000,000 \times \left(\frac{0.060}{12}\right) = \$15,000.00$$
* Total Monthly Payment: $15,000.00
* Principal Reduction: $0.00
* Loan Balance at Month 36: $3,000,000 (unchanged)
2. The Amortizing Phase (Years 4 to 10)
At Month 37, the interest-only period ends, and principal amortization begins. However, because 3 years have elapsed without principal paydown, the lender must recalculate principal reduction over the remaining 22 years of the original 25-year amortization schedule.
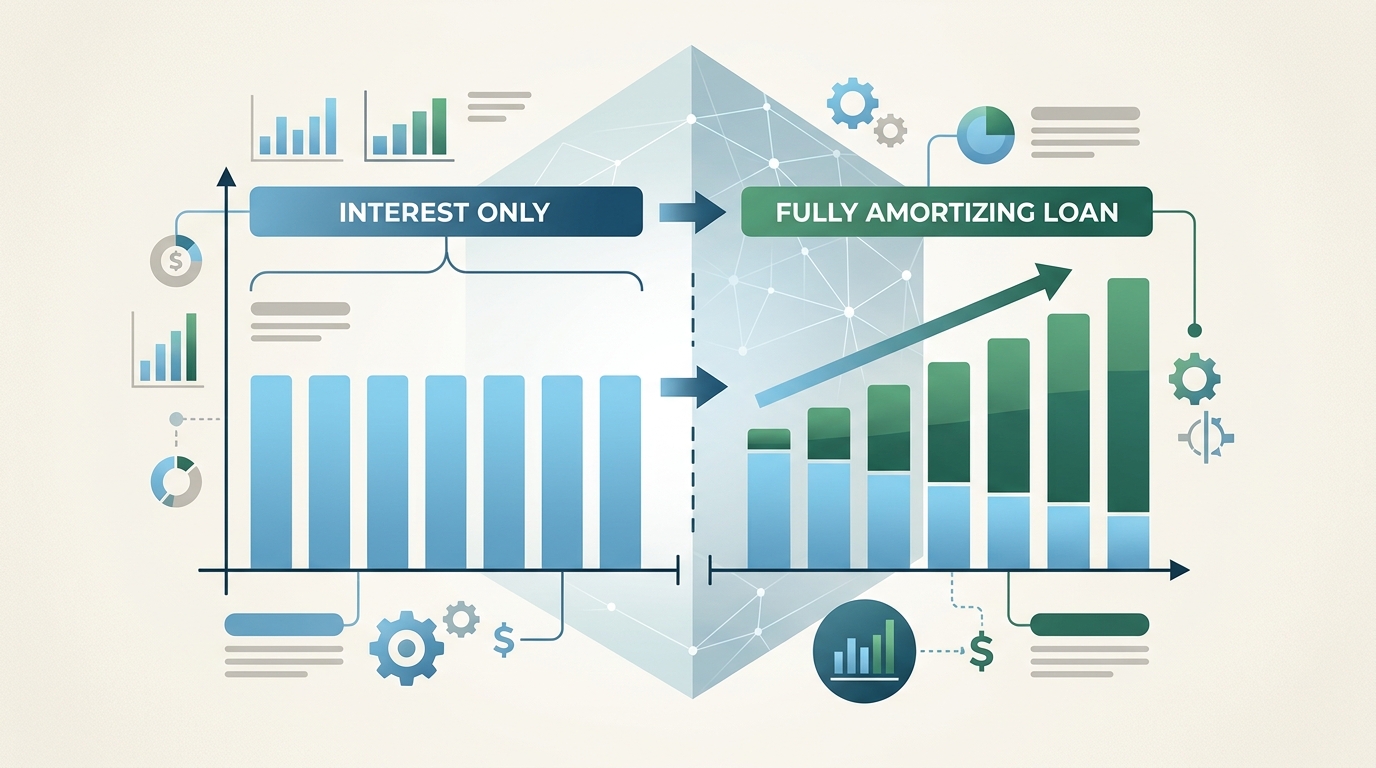
The transition from an interest-only period to a fully amortizing schedule results in a significant increase in monthly debt service.
- Recalculated Monthly Payment: Based on $3,000,000 amortized over 22 years (264 months) at 6.00% interest.
- New Monthly Payment: $20,537.14
- Payment Increase: Monthly debt service increases by $5,537.14 per month (+36.9%).
This dramatic payment increase is known as payment shock. Understanding how standard amortization works is essential before committing to an interest-only structure.
Benefits of Interest-Only Periods for CRE Investors
Interest-only structures offer several compelling advantages when aligned with specific commercial real estate investment strategies.
1. Cash Flow Maximization and Higher Initial Returns
By waiving principal reduction, monthly debt service is minimized. This boosts immediate net cash flow and increases year-one Cash-on-Cash yields, providing higher cash distributions to equity partners.
2. Alignment with Value-Add and Stabilization Strategies
When acquiring underperforming commercial assets, initial cash flows may be depressed during property re-tenanting or capital improvement programs. An interest-only period of 12 to 36 months provides crucial cash flow relief while the owner executes physical renovations and increases rents to market levels.
3. Increased Debt Service Coverage Ratio (DSCR) Cushion
Lower initial monthly payments reduce annual debt service, creating a higher initial DSCR during lease-up phases:
* Amortizing Debt Service ($19,329/mo): Annual Debt Service = $231,948
* Interest-Only Debt Service ($15,000/mo): Annual Debt Service = $180,000
* Resulting Impact: Lowers annual debt service burden by $51,948, providing a significant safety margin for property underwriting.
4. Opportunity Cost and Capital Flexibility
Instead of allocating cash toward principal paydown, real estate sponsors can reinvest operational savings into higher-yielding opportunities, such as tenant improvements, property upgrades, or secondary property acquisitions.
The Risks and Drawbacks of Interest-Only Structures
While interest-only commercial real estate loans offer substantial liquidity benefits, they also introduce specific risks that investors must manage actively.
1. Payment Shock at Transition
When the I/O window closes, monthly debt payments jump significantly. If property Net Operating Income (NOI) has not grown sufficiently during the interest-only period to cover the higher amortizing payment, the property’s cash flow and DSCR will decline rapidly.
2. Lack of Principal Equity Accumulation
Because no principal is paid down during the I/O phase, equity growth relies entirely on property market appreciation and NOI growth. If market values decline, the owner’s equity cushion erodes faster than on an amortizing loan.
3. Heightened Refinancing and Balloon Risk
At maturity, the outstanding principal balance remains equal to the original loan amount. This increases maturity risk if property values fall or interest rates rise when paying off balloon payments at the end of the loan term.
Interest-Only Commercial Mortgage Qualification Requirements
Lenders view interest-only commercial real estate loans as carrying higher risk than fully amortizing debt. Consequently, underwriting requirements for I/O terms are stricter:
- Lower Maximum Loan-to-Value (LTV): While amortizing debt can reach 75% LTV, lenders typically cap interest-only loans at 60% to 65% LTV to maintain an adequate equity cushion.
- Higher Minimum DSCR Benchmarks: Lenders underwrite DSCR based on full amortizing payments rather than the lower interest-only payment, requiring a minimum DSCR of 1.25x to 1.35x on a fully amortizing basis.
- Prime Property Quality & Asset Location: Full-term or multi-year interest-only periods are generally reserved for Class A and B properties in strong primary or secondary metropolitan markets.
- Strong Sponsor Net Worth & Liquidity: Lenders require experienced borrowers with substantial net worth (typically equal to or exceeding the loan amount) and significant post-closing liquidity reserves.
To evaluate how interest-only periods change your specific project debt service, you can calculate your interest-only payments using our online calculator.
Frequently Asked Questions (FAQ)
Can you get a full-term interest-only commercial real estate loan?
Yes. Full-term interest-only loans (where no principal is paid over the entire 5 or 10-year loan term) are available through CMBS lenders, life insurance companies, and agency multifamily programs, primarily for low-LTV (e.g., <=60%) and high-quality assets. (life insurance companies)
How long do interest-only periods typically last on commercial loans?
Standard interest-only periods on commercial bank debt usually range from 1 to 3 years for value-add acquisitions, while 5 to 10-year interest-only terms are achievable on institutional CMBS or agency debt packages.
Are interest rates higher on interest-only commercial real estate loans?
Sometimes. Depending on market liquidity and lender policy, lenders may add a premium of 0.125% to 0.375% to the interest rate on interest-only loans to compensate for the delayed principal repayment risk.
What happens if property NOI does not increase before the interest-only period ends?
If NOI fails to grow before full amortization begins, debt service coverage will decline, reducing net cash flow to investors. In severe cases, owners may need to inject additional capital, negotiate a loan modification, or refinance the debt early.