
Understanding the Commercial Real Estate Underwriting Process
The commercial real estate underwriting process is the analytical backbone of commercial lending. After an applicant submits a loan package, credit analysts and underwriters perform a rigorous risk assessment to determine whether the subject property generates sufficient cash flow to service requested debt while insulating the financial institution against default.
For commercial real estate investors, developers, and corporate borrowers operating in 2026, understanding how lenders evaluate risk allows you to present financial data accurately, anticipate underwriter queries, and position your property for smooth approval.
This guide explores the analytical methodology behind cre underwriting steps, detailing the core evaluation criteria, mandatory financial ratio benchmarks, underwriting timelines, and critical red flags to avoid.
What is the Commercial Real Estate Underwriting Process?
The commercial real estate underwriting process is an in-depth financial audit conducted by a lender to evaluate the creditworthiness of a borrower, the structural integrity and valuation of property collateral, and the net operating cash flows available for debt repayment.
Unlike residential underwriting—which focuses primarily on borrower credit scores and personal W-2 income—commercial underwriting centers on property economics. While borrower creditworthiness remains important, underwriters view the commercial property as the primary source of loan repayment and the physical land/building as collateral protection.
The underwriting phase begins once initial document collection is complete and continues through final Credit Committee approval, serving as the bridge between preliminary application and formal loan commitment. To understand where underwriting fits into the overall timeline, consult our step-by-step overview on the processing and underwriting stages of a commercial loan.
How Do Lenders Evaluate a Commercial Property Loan Application?
During commercial lender risk evaluation, credit committees utilize a classic framework adapted specifically for real estate assets: The 5 Cs of Commercial Credit.
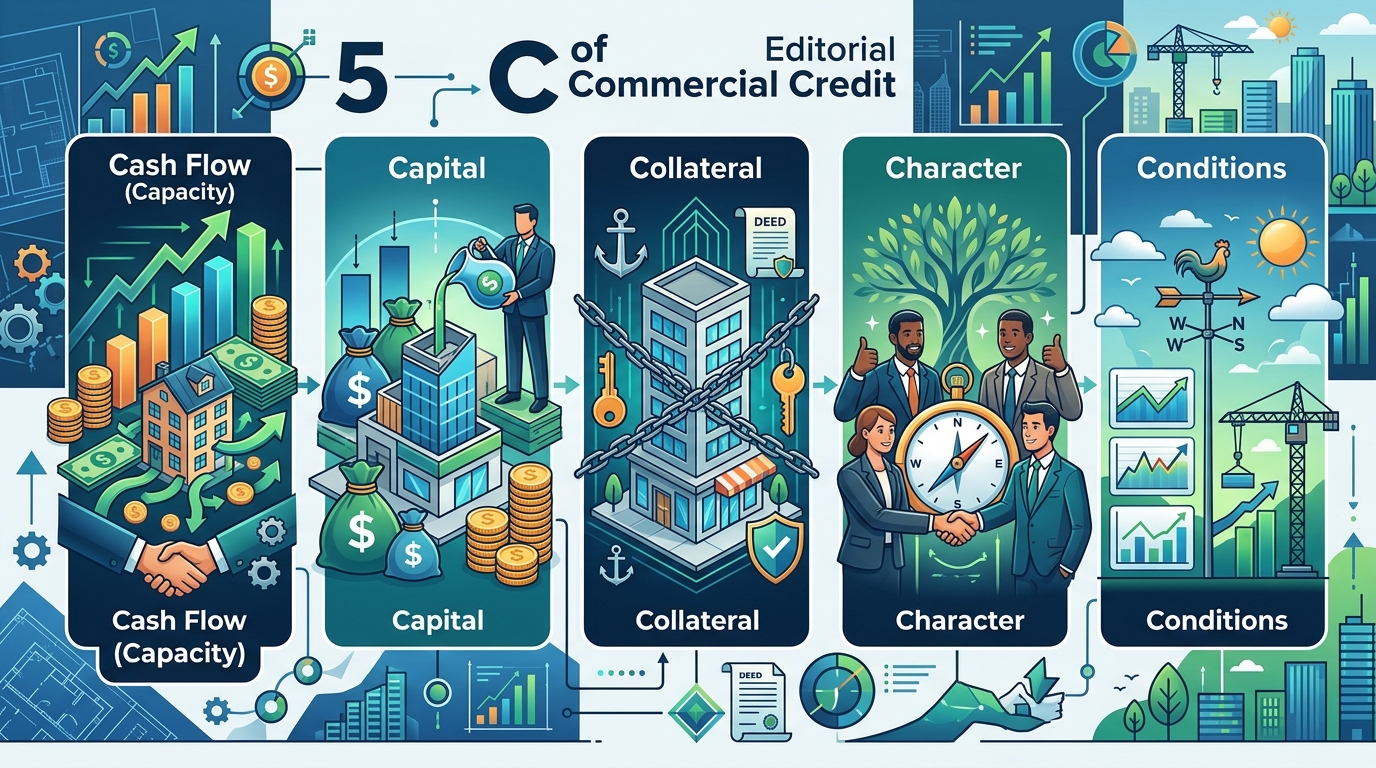
Lenders evaluate commercial property loan applications using the ‘5 Cs of Commercial Credit’ framework, assessing Cash Flow, Capital, Collateral, Character, and Conditions.
- Cash Flow (Capacity): The property’s ability to generate sufficient Net Operating Income (NOI) to cover proposed monthly principal and interest payments. Underwriters stress-test cash flows against rising interest rates and potential vacancy spikes.
- Capital: The amount of equity cash the borrower invests into the transaction. Higher borrower equity (down payment) aligns interests and reduces lender loss severity in the event of default.
- Collateral: The physical real estate asset securing the mortgage loan. Underwriters evaluate property condition, geographic market location, asset class demand, and third-party appraised market value.
- Character: The reputation, industry experience, net worth, liquidity, and credit history of the borrowing entity and personal guarantors.
- Conditions: Macroeconomic and local market factors influencing the property, including local job growth, competitive supply pipelines, lease structure terms, and prevailing interest rate environments.
Key Financial Ratios in the Underwriting Decision
To establish objective approval criteria during dscr commercial loan underwriting, lenders apply strict mathematical benchmarks across key financial ratios.
What DSCR Ratio Do Commercial Lenders Look For?
The Debt Service Coverage Ratio (DSCR) is the single most critical metric evaluated during commercial real estate underwriting. It measures a property’s annual Net Operating Income (NOI) relative to its annual Debt Service (principal + interest payments).
🧮 FORMULA CALLOUT: Debt Service Coverage Ratio (DSCR)
$$\text{DSCR} = \frac{\text{Net Operating Income (NOI)}}{\text{Annual Debt Service (Principal + Interest)}}$$
- Standard Lender Benchmark: 1.20x to 1.35x
- Example: If a commercial building generates $125,000 in Net Operating Income and annual mortgage payments total $100,000, the DSCR is 1.25x ($125,000 ÷ $100,000).
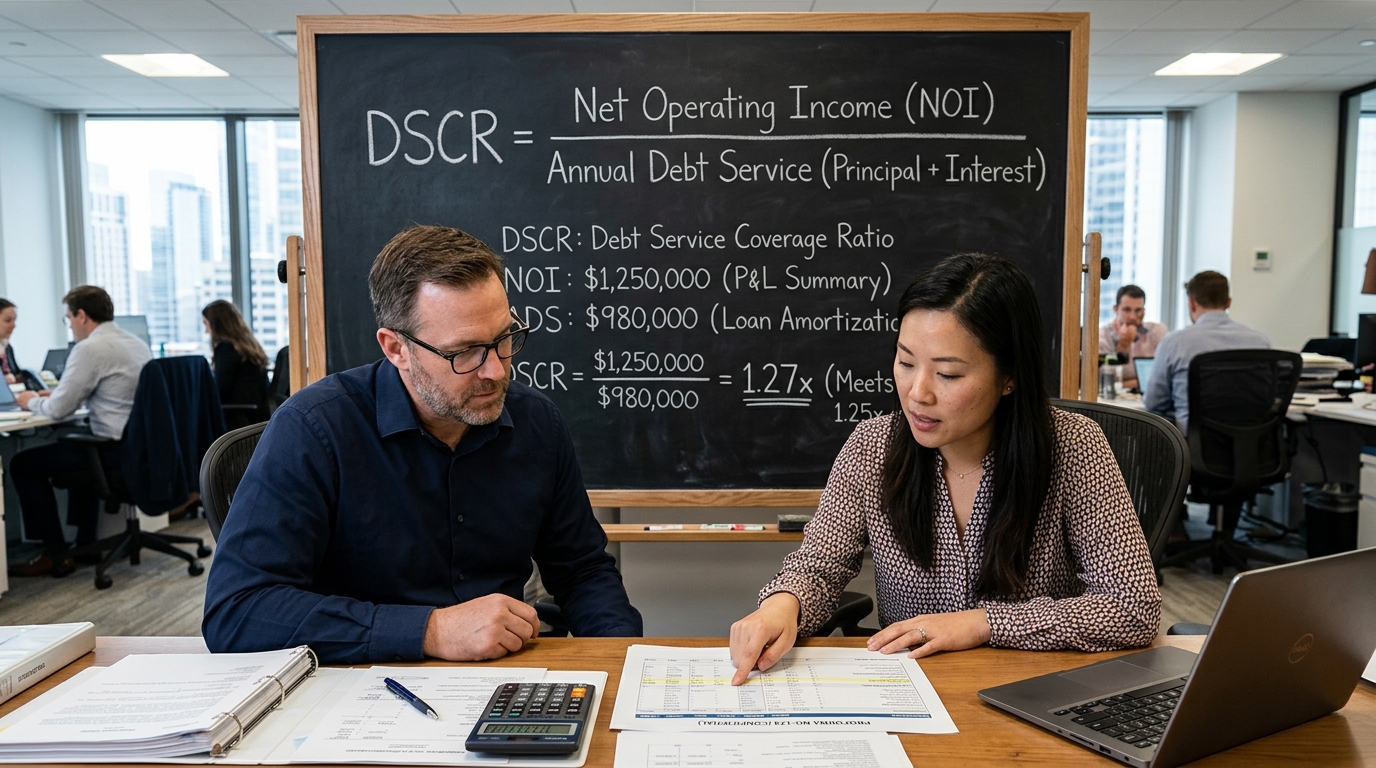
The Debt Service Coverage Ratio (DSCR) formula is a critical metric in commercial real estate underwriting, measuring a property’s ability to cover its annual debt obligations.
A DSCR of 1.25x means the property generates 25% more cash flow than required to cover annual loan obligations, providing a safety cushion against unexpected operating expenses or tenant vacancies. Properties falling below 1.20x DSCR are standardly declined or forced to reduce loan size until coverage targets are met.
Loan-to-Value (LTV) and Debt Yield Requirements
Beyond DSCR, underwriters enforce strict caps on leverage and performance yield:
- Loan-to-Value (LTV) Ratio: Measures loan size against appraised property value. Conventional commercial banks cap LTV at 65% to 75%, whereas government-backed SBA programs reach up to 85% to 90% for owner-occupied properties.
- Debt Yield: Measures lender cash return independent of loan interest rates or amortization length:
$$\text{Debt Yield} = \frac{\text{Net Operating Income (NOI)}}{\text{Total Loan Amount}}$$
Commercial lenders generally require a minimum Debt Yield of 8.5% to 10.0%, ensuring safety in fluctuating interest rate environments.
Before submitting financial disclosures, verify your binder meets these metrics by consulting our list of mandatory commercial loan application requirements.
The CRE Underwriting Time Frame: Inside the Process
The commercial real estate underwriting phase standardly requires 14 to 30 days within the broader 60-day loan closing window.
Here is an inside look at how credit analysts process a submission:
- Days 1–5: Financial Spreading & Stress Testing: Credit analysts audit tax returns, balance sheets, and trailing 12-month operating statements, reconstructing income statements to eliminate non-recurring expenses or unverified revenue.
- Days 6–15: Third-Party Report Review: Underwriters review independent third-party reports, including certified property appraisals, Phase I Environmental Site Assessments (ESA), site surveys, and property condition assessments (PCA).
- Days 16–20: Credit Memo Preparation & Committee Submission: The underwriter compiles a comprehensive Credit Memorandum summarizing property strengths, risks, guarantor net worth, DSCR compliance, and loan structure covenants, presenting the file to Credit Committee for approval decision.
Common Red Flags During Lender Risk Evaluation
Identifying potential underwriting obstacles before formal submission prevents credit denial:
- Unverified Lease Income or Single-Tenant Rollover Risk: Over-reliance on a single tenant whose lease expires within 12–24 months creates cash flow vulnerability that underwriters will flag.
- Inconsistent Tax Returns vs. Internal Financial Statements: Significant variances between net income reported on IRS tax returns and income shown on internal Profit & Loss statements trigger audit holds.
- Deferred Property Maintenance: Physical issues flagged in Property Condition Assessments (e.g., roof repair needs, HVAC replacement) require escrow holdbacks or immediate repair funds prior to closing.
- Insufficient Guarantor Liquidity: Failing to demonstrate post-closing liquid cash reserves equal to 6–12 months of mortgage payments can stall credit committee sign-off.
Preparing to apply for commercial property financing? Read our complete guide on applying for commercial real estate financing to structure your documentation and secure favorable loan terms.