

Commercial Mortgage Prepayment Penalties: Yield Maintenance, Defeasance & Step-Down Fees
Introduction: The Capital Cost of Early Commercial Loan Payoffs
When financing commercial real estate with long-term senior debt, exit strategy planning requires a thorough understanding of early payoff provisions. Institutional lenders—such as life insurance companies, CMBS conduit lenders, and Fannie Mae/Freddie Mac agency syndicators—price commercial debt based on predictable, long-term yield projections.
If a borrower pays off a fixed-rate commercial mortgage prior to maturity—whether through a property sale, a debt refinance, or capital recapitalization—the lender loses anticipated interest income. To protect their yield, lenders enforce strict commercial mortgage prepayment penalties.
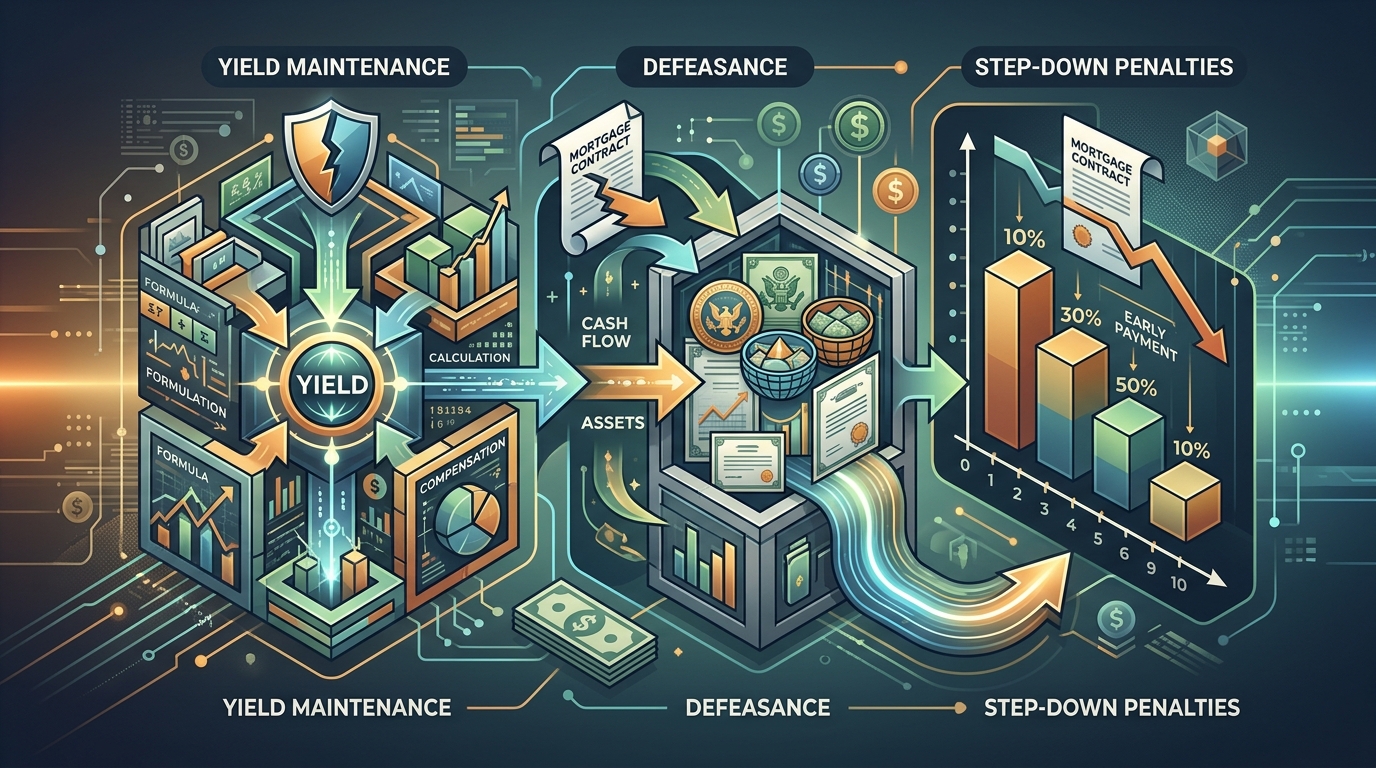
Lenders employ various mechanisms, including yield maintenance, defeasance, and step-down penalties, to protect their anticipated yield when commercial mortgages are paid off prior to maturity.
Understanding the financial mechanics behind Yield Maintenance, Defeasance, and Step-Down structures is essential for real estate investors and CFOs seeking to prevent multi-million-dollar exit penalties.
What Are Commercial Mortgage Prepayment Penalties?
A commercial mortgage prepayment penalty is a contractual fee assessed when a borrower pays off a commercial loan balance prior to its scheduled maturity date. Prepayment penalties are structured to compensate debt holders for loss of yield and are calculated using one of three primary mechanisms: Yield Maintenance, Defeasance, or Step-Down (Declining Scale) percentages.
For a comprehensive review of upfront closing costs and ongoing financing expenses, explore our broader commercial mortgage fee structure.
The Three Main Types of Prepayment Penalty Calculations
Different capital providers utilize specific prepayment structures based on their funding sources and securitization models.

A visual comparison of Yield Maintenance, Defeasance, and Step-Down prepayment structures, highlighting their distinct characteristics and applications in commercial mortgages.
1. Yield Maintenance
Yield Maintenance is a financial formula designed to make the lender whole by paying them the present value of the interest income they would have earned over the remaining loan term, minus current market reinvestment yields.
- Calculation Formula: The penalty equals the present value of remaining scheduled monthly interest payments, discounted at the prevailing U.S. Treasury rate corresponding to the remaining maturity window.
- The Interest Rate Sensitivity Factor: Yield maintenance penalties fluctuate inversely with prevailing interest rates. If interest rates drop after you secure your mortgage, your yield maintenance penalty increases dramatically because the lender cannot re-lend money at your original higher note rate.
- Minimum Yield Maintenance Floor: Most yield maintenance clauses include a minimum fee floor (typically 1.0% of the remaining principal balance), ensuring the lender receives a baseline penalty even if interest rates rise.
2. Defeasance
Common in CMBS (Commercial Mortgage-Backed Securities) and conduit loans, Defeasance is not a monetary penalty paid directly to the lender. Instead, defeasance is a collateral substitution process.
- How Defeasance Works: The borrower replaces the commercial real estate collateral with a portfolio of risk-free U.S. Treasury securities that produce exact cash flows matching the mortgage’s remaining principal and interest payment schedule.
- Third-Party Defeasance Overhead Costs: Executing a defeasance requires hiring specialized third-party advisors, including defeasance consultants, bond brokers, independent CPA accounting firms, and specialized legal counsel.
- Total Defeasance Expense: In addition to purchasing the required Treasury bond portfolio, borrowers face $25,000 to $50,000+ in administrative defeasance fees to complete the collateral release.
3. Step-Down / Declining Scale Penalties
Preferred by commercial banks, portfolio lenders, and private debt funds, Step-Down prepayment penalties assess a fixed percentage penalty that decreases for each year the loan remains outstanding.
- Structure Examples:
- 5-Year Loan (5-4-3-2-1%): 5% penalty in Year 1, 4% in Year 2, 3% in Year 3, 2% in Year 4, and 1% in Year 5.
- 3-Year Loan (3-2-1%): 3% penalty in Year 1, 2% in Year 2, and 1% in Year 3.
- Predictability Advantage: Unlike Yield Maintenance or Defeasance, step-down penalties are completely independent of market interest rate fluctuations. Borrowers can calculate their exact payoff cost on day one.
Comparison Matrix: Yield Maintenance vs. Defeasance vs. Step-Down
The following matrix compares structural features across the three primary prepayment penalty categories:
| Feature | Yield Maintenance | Defeasance | Step-Down (Declining Scale) |
|---|---|---|---|
| Primary Lenders | Life Cos, Fannie/Freddie, CMBS | CMBS, Conduit Lenders | Commercial Banks, Debt Funds |
| Mechanic | Cash Penalty Payment | Treasury Bond Substitution | Fixed Percentage of Principal |
| Rate Sensitivity | High (Penalty rises if rates fall) | High (Bond portfolio cost rises) | None (Fixed percentage schedule) |
| Third-Party Fees | Low ($2,000 – $5,000 legal) | High ($25,000 – $50,000+ advisory) | None |
| Prepayment Flexibility | Low | Low | Moderate to High |
| Best For | Long-Term Hold (10+ Years) | Securitized CMBS Capital | Value-Add & Short-to-Mid Holds |
To examine how short-term debt structures handle exit charges, read our guide on bridge loan origination and exit fee charges.
Commercial Loan Exit Fees vs. Prepayment Penalties
Borrowers often confuse prepayment penalties with commercial loan exit fees. While both represent charges incurred when paying off debt, their operational definitions differ significantly:

While both are charges upon loan payoff, prepayment penalties apply to early payoffs, whereas exit fees are mandatory regardless of payoff timing.
- Prepayment Penalty: A penalty for paying off a loan earlier than scheduled maturity. If you hold the loan to maturity, zero prepayment penalty applies.
- Commercial Loan Exit Fee: A mandatory fee (typically 0.50% to 1.00% of loan proceeds) assessed upon loan payoff, regardless of when payoff occurs. Exit fees are common in bridge financing and construction debt to increase lender total yield.
Open Prepayment Windows
Most institutional commercial mortgages feature an Open Prepayment Window during the final 3 to 6 months of the loan term. During this open window (e.g., months 115–120 on a 10-year term), borrowers can pay off the remaining principal in full with zero prepayment penalty or defeasance requirements.
Frequently Asked Questions
How are commercial mortgage prepayment penalties calculated?
Commercial mortgage prepayment penalties are calculated using three primary methods:
1. Yield Maintenance: A formula calculating the present value of lost interest income discounted at prevailing U.S. Treasury rates.
2. Defeasance: Purchasing a portfolio of U.S. Treasury bonds to replace real estate collateral.
3. Step-Down Scale: A fixed declining percentage (e.g., 5-4-3-2-1%) applied to the remaining loan balance.
What is a commercial loan exit fee?
A commercial loan exit fee is a mandatory charge (typically 0.50% to 1.00%) assessed by bridge lenders or debt funds upon final loan payoff. Unlike prepayment penalties, exit fees are charged regardless of whether the loan is paid off early or held to full maturity.
Which prepayment structure is best for short hold periods?
For short hold periods (1 to 5 years), a Step-Down penalty or a bridge loan with an open prepay clause after 12 months is ideal. Yield maintenance and defeasance structures should be avoided for short hold periods due to high rate sensitivity and heavy third-party fees upon early exit.
Strategic Playbook: Negotiating Prepayment Flexibility in Term Sheets
To maintain strategic flexibility and protect capital during property disposition or refinancing, real estate borrowers should negotiate prepayment terms during initial term sheet discussions.
Negotiation Tactics for Borrowers
- Request a Step-Down Conversion: Ask the lender to replace yield maintenance language with a predictable step-down schedule (e.g., 3-2-1%).
- Expand the Open Prepayment Window: Negotiate to expand the final open prepay window from 30 days to 90 or 180 days prior to maturity.
- Secure Refinance Penalty Waivers: Request a clause waiving all prepayment penalties if the property is refinanced using the same lending institution.
- Incorporate Lockout Periods Wisely: If a lender insists on a 2-year prepayment lockout, ensure the lockout converts directly to an open prepay or low step-down fee in year 3.
For actionable advice on negotiating loan documents, consult our guide on negotiating flexible prepayment terms.
To understand broader mortgage operational timelines and payoff procedures, see our resource on commercial loan payoff and maturity mechanics.